
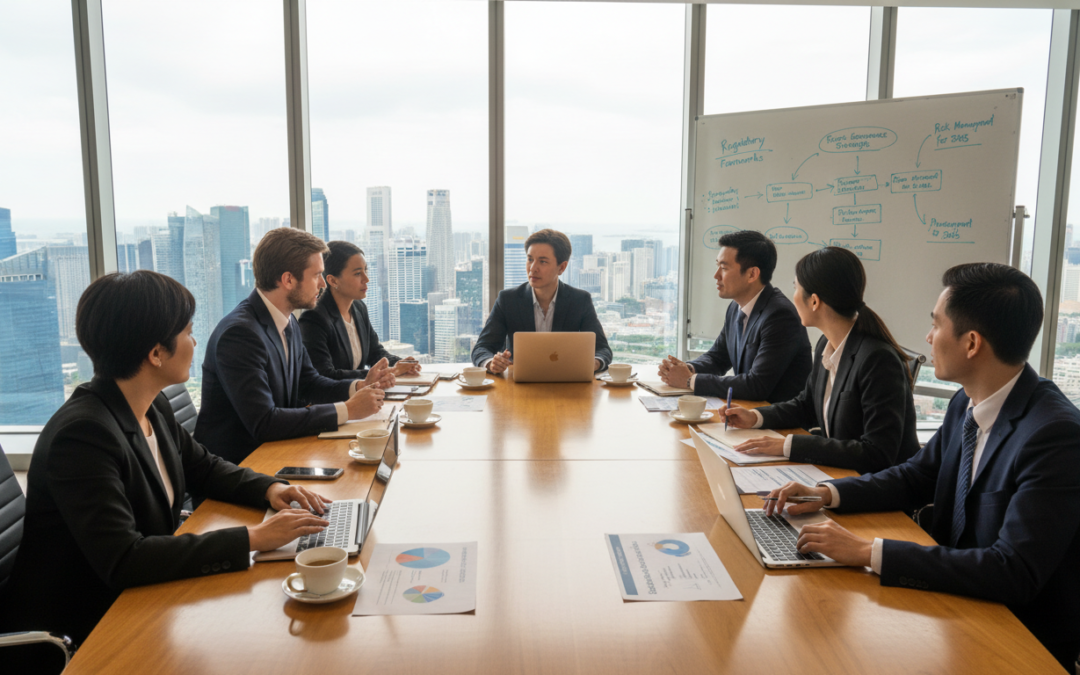
“To improve is to change; to be perfect is to change often.” — Winston Churchill
This guide explains, in practical terms, how decisions are made, who is accountable, and how risks and controls protect stakeholders in a Singapore business setting.
It outlines the hybrid system: mandatory rules under the Companies Act and the Securities and Futures Act for listed firms, plus the Code of Corporate Governance operating on a comply or explain basis.
The piece draws a clear line between what is legally required and what is best practice as companies grow. You will see why lenders and investors often benchmark against listed-company standards.
Expect a 2026 perspective that values working systems — board records, approvals and oversight — not merely policies on paper. We also note real consequences: fines, reputational harm, bank delays and director exposure.
Key Takeaways
- Understand the dual system: Companies Act plus the Code of Corporate Governance.
- Know the baseline legal duties and the scalable best practices for boards and reporting.
- Practical oversight matters more than paperwork when regulators review records.
- Poor practice can lead to fines, reputational damage and personal liability for directors.
- This guide targets businesses in Singapore and foreign owners with actionable steps.
Why corporate governance matters for Singapore SMEs in 2026
In 2026, small and medium businesses face closer scrutiny over how they make decisions and record them. Informal arrangements and verbal agreements no longer shield companies from challenge. Counterparties and regulators now look for clear accountability and visible oversight in day-to-day dealings.
From “SME exemption mindset” to real accountability
SME leaders must move from an exemption mindset to active stewardship. Directors are expected to review results, query unusual transactions and ensure controls exist beyond signatures. This is practical accountability, not box-ticking.
Commercial pressure from banks, investors and grant authorities
Funding partners now assess governance quality as part of credit and investment decisions. Better practices speed lending, improve investor confidence and raise the odds of grant success. Weak structures slow approvals and increase perceived risks.
How failures surface: disputes, audits and exits
Breakdowns usually appear during shareholder fights, audits, due diligence for exits or regulatory reviews. Missing minutes, unclear approvals and undocumented related-party dealings are common triggers.
- Family-run firms often show blurred lines between personal and company spending.
- Simple controls—documented decisions and routine review—reduce fraud and misunderstanding.
- Strong compliance and recorded oversight are the first line of defence when questions arise.
Singapore’s corporate governance framework structure and the dual-system approach
The local framework pairs clear statutory duties with flexible, market-led standards. This two-track model separates what companies must do by law from what markets expect for credibility.
Mandatory rules vs best-practice expectations
Mandatory rules include filings under the Companies Act, director duties, and basic accounting records. These are legal obligations: miss them and penalties follow.
Best-practice items are recommended: board independence, committees, risk oversight and richer disclosure to stakeholders. They lift market trust but remain adaptable.
How the code works in practice
The Code of Corporate Governance operates on a comply or explain basis. Listed entities must follow code provisions or explain honest alternatives in annual reports. Explanations must show how the intent of the provision is met.
Where the Securities Futures Act strengthens disclosure
The SGX Listing Manual and the Securities Futures Act add a listed-layer. The SFA makes reckless or intentional disclosure failures criminal, while negligent lapses can bring civil penalties. That overlay explains why partners often ask for listed-style disclosure and information.
| Layer | Source | Key focus |
|---|---|---|
| Statutory | Companies Act | Filings, director duties, accounts |
| Market | Code of Corporate Governance | Board practice, committees, risk |
| Listed overlay | SGX Manual & Securities Futures Act | Enhanced disclosure and enforcement |
For practical terms and policies, check the terms and conditions used by many advisers. Next we outline the regulators who supervise these layers.
Regulators and enforcement: ACRA, MAS and SGX
Three agencies share oversight of company conduct, each with distinct powers and focus. Their roles shape how firms meet legal and market expectations and influence day-to-day compliance and risk management.
ACRA: registrar and statutory enforcer
ACRA administers the Companies Act, handles incorporation filings and pursues breaches. Persistent non-compliance or filing failures can lead to penalties and director disqualification. Such actions are personal and can bar individuals from holding directorships.
MAS: central bank, regulator and Code issuer
MAS regulates financial firms, issues the Code of Corporate Governance and publishes guidance that raises baseline expectations. MAS enforces prudential rules and nudges better oversight across the financial sector.
SGX: market rules and disclosure enforcement
For listed companies, SGX polices the Listing Manual, tackles disclosure failures and can fine up to S$250,000 per contravention. Market breaches often trigger corrective programmes or education requirements.
- Enforcement often begins with SGX for market breaches, then escalates to statutory probes for suspected legal offences.
- The July 2025 S$27.45 million in penalties shows regulators will quantify costs for weak practices.
- Strong governance reduces regulator contact and speeds responses when authorities seek documents or explanations.
Companies Act obligations every SME must meet
Statutory duties require more than paperwork; they shape everyday choices in a company. Directors must turn legal standards into routine checks and clear records.
Director conduct under Section 157
Section 157 demands honesty and reasonable diligence. Practical behaviours include asking pointed questions, reading management accounts and challenging unexplained transactions.
Company secretary and timeline
A company must appoint a company secretary within three months of incorporation. Good secretarial support ensures timely filings, properly drafted resolutions and defensible minutes.
Accounting, AGMs and dividends
Maintain proper accounting records and present financials where an AGM applies. Pay dividends only from profits and document the board’s reasoning to show due diligence.
Conflicts, disclosure and false statements
Disclose conflicts, obtain written approvals and have conflicted directors abstain. False statements in company documents can attract fines up to S$50,000 and up to two years’ imprisonment.
“Treat simple controls as your first line of defence: review, record and retain.”
Corporate governance requirements Singapore SME: what “good” looks like beyond the minimum
Good oversight starts with habits you can sustain. Documented decisions, written resolutions and a clear approval matrix turn informal choices into trusted practice. These steps do not over-engineer; they protect value and speed up routine work.
Documented decisions and board records
Keep concise minutes and sign-off notes for material commitments. Clear records help answer “why” during audits, disputes or banking checks.
Separating owners and management
When owners step back from day-to-day management, conflicts drop and transparency rises. Simple rules—declared interests and recusal—protect minority stakeholders and strengthen accountability.
Financial discipline and review cadence
Adopt monthly bookkeeping, a monthly management review of cash flow and key variances, and a quarterly director-level review. This cadence catches cash issues early and supports better decision-making.
Scaling controls with growth
Use an annual governance review to add approvals, reporting depth and reconciliations as headcount, revenue and transaction volume increase. Evolving controls keep operational risks manageable and improve overall performance.
| Area | Minimum step | Practical next step |
|---|---|---|
| Decision records | Signed resolutions | Minute index and retention policy |
| Owner/management split | Conflict disclosures | Written delegation matrix |
| Financial controls | Basic bookkeeping | Monthly reviews and reconciliations |
“Treat simple controls as your first line of defence: review, record and retain.”
Board composition, independence and leadership structure
A well-composed board shapes strategy, tests risk assumptions and lifts management performance.
Why composition matters: the right skills mix improves decision quality, strengthens risk challenge and boosts oversight. Even private firms gain when directors bring accounting, sector and legal experience to the table.
Board effectiveness: skills mix, diversity policies and transparency
Practical effectiveness means clear role descriptions, a regular meeting cadence and concise pre-reads. Directors should get timely papers so they can ask informed questions.
Adopt simple diversity policies and report how appointments support performance and investor confidence.
Chairman and CEO separation
Separating the chairman and CEO reduces concentration of power and improves challenge. Where roles combine, ensure extra independent scrutiny and documented mitigating steps.
Independence rules and SME adaptations
Listed companies must aim for at least one-third independent directors under the Code. SMEs can borrow this principle by appointing a genuinely independent adviser or non-executive director to oversee key transactions.
Director tenure and independence assessments
Long tenures can erode independent challenge. Many frameworks flag reassessment after about nine years. Record independence considerations and the rationale for each appointment.
“Documented independence checks and clear leadership splits make oversight visible to shareholders and lenders.”
| Area | Practical rule | SME adaptation |
|---|---|---|
| Skills mix | Board includes finance, industry and legal experience | Invite one external adviser with relevant expertise |
| Leadership split | Separate chairman and CEO (listed) | Designate senior independent director if roles combine |
| Independence | At least one-third independent directors (listed) | Appoint one independent non-exec and document conflict checks |
Board committees and oversight: when you need them and how they work
Committees turn board discussion into disciplined scrutiny and clearer accountability. They add specialist review where directors need depth—on finance, pay and appointments—without expanding routine meetings.
Mandatory committees for listed companies
Listed companies must set up Audit, Remuneration and Nominating committees with written terms of reference under the code. These three panels form the benchmark many lenders and investors expect.
Audit Committee: duties and expertise
The Audit Committee safeguards reporting integrity, monitors auditor independence and reviews internal controls. It typically has at least three non-executive members, a majority independent, and at least two with recent accounting or financial expertise.
Auditors should meet the committee without management present at least once a year so concerns can be raised directly.
Remuneration and Nominating Committees
Remuneration panels align pay with long-term performance and reduce conflicts. Nominating groups handle appointments, succession planning and an annual independence review of directors.
Practical SME pathway: start with an audit-and-risk working group or external advisory panel. Formalise committees as transaction volume, shareholders or related-party activity grow.
code corporate governance guidance
Financial reporting, disclosure and accountability requirements
Clear, timely financial reporting is the backbone of lender and investor confidence for any growing company. Annual statements turn raw accounting into decision-useful information. They also show whether internal checks are working.
Annual statements and ACRA filing
All companies must prepare annual financial statements and file them with ACRA. Filings are submitted in XBRL format, so accounting systems must produce tagged data that meets ACRA specifications.
Practical tip: schedule internal sign-offs and reconciliations at least four weeks before the filing deadline to avoid last-minute errors.
When an audit is triggered
An audit is generally required if a company meets two of these three criteria for two consecutive years: total assets exceed S$10m; annual revenue exceeds S$10m; or it employs more than 50 staff. Growing firms should monitor these thresholds to plan audit budgets and timelines.
Listed disclosure duties and legal exposure
Listed companies face continuous disclosure duties under SGX rules. The Securities and Futures Act can impose criminal liability for intentional or reckless disclosure failures and civil exposure for negligent lapses.
This higher duty makes timeliness and accuracy essential for market issuers and offers lessons for private firms on disciplined reporting.
Why this matters for oversight and capital: accurate accounting records reduce inconsistencies across filings. Lenders and investors rely on consistent, decision-useful information to assess risk and value. Poor filings slow access to capital and raise questions at due diligence.
“Maintain a board review calendar, run monthly variance analysis and keep documented queries to show clear oversight.”
| Stage | Action | Outcome |
|---|---|---|
| Preparation | Monthly bookkeeping and reconciliations | Clean trial balance for year-end |
| Sign-off | Management and board review, documented questions | Clear approvals and audit trail |
| Filing | XBRL tagging and ACRA submission | Regulatory compliance and searchable data |
| Listed reporting | Continuous disclosure under SGX/SFA | Market transparency and higher legal stakes |
Risk management, internal controls and data responsibility
Boards must treat risk as an ongoing management task, not a one-off checklist. The board’s job is to ensure a system exists that covers financial, operational, compliance and IT risks. That system should name owners, set reporting cadence and define escalation paths.
Practical risk model for SMEs
Adopt a simple map: list top risks by category, assign an owner, and set monthly or quarterly reporting. Review this at board level annually.
Internal controls as business hygiene
Apply dual authorisation for payments, clear approval limits, separation of invoice processing and bank reconciliation reviews. These basic controls reduce errors and fraud.
Assurance, data and local oversight
Use quarterly CEO/CFO assurance statements to create executive accountability. Treat data as an asset: vet vendors, require contractual controls, enforce access rules and maintain a tested incident response plan.
Foreign-owned entities should show real local director oversight and documented substance. This reduces banking friction and investor questions.
| Topic | Immediate step | Benefit |
|---|---|---|
| Risk mapping | Assign owners & reporting | Clear accountability |
| Payments | Dual authorisation | Fewer losses |
| Data | Vendor due diligence & IR plan | Faster breach response |
| External support | Outsource finance/secretarial | Cost-effective expertise |
“Strong risk practice speeds access to capital and builds confidence with lenders.”
Conclusion
Practical controls and clear records turn regulatory friction into business advantage.
For a company in this market, the main takeaway is simple: meet statutory obligations under the Companies Act and follow best-practice layers to win trust. Good practice reduces delays, fines and personal exposure for directors.
Non-negotiables: keep proper minutes, document approvals, disclose conflicts, and run disciplined financial reporting. These steps protect shareholders and owners by creating clear accountability and stronger valuations at exit.
Next steps: schedule an annual governance review, set approval limits, tighten risk and data controls, and improve board reporting. Many firms use specialist services for secretarial work, filings and minute-taking to avoid missed deadlines.
See practical best practices to turn compliance into a growth enabler: better access to capital, fewer surprises and stronger market credibility.
FAQ
What are the basic legal duties of directors under the Companies Act?
How does the Code of Corporate Governance apply to small and medium enterprises?
When must a company appoint a company secretary and why is this important?
Which regulators oversee governance and enforcement in Singapore?
What triggers a statutory audit for Singapore companies?
How should conflicts of interest be handled and recorded?
What are practical steps SMEs can take to improve oversight without heavy cost?
Do SMEs need formal board committees like listed companies?
What disclosure obligations apply when a company prepares financial statements?
How can boards assess director independence and tenure appropriately?
What are the key internal control practices SMEs should adopt now?
How do data protection and vendor oversight fit into governance expectations?
What consequences follow from making false statements in company documents?
How does separation of Chair and CEO roles improve oversight?
What should foreign-owned entities demonstrate to meet local oversight expectations?
Where can directors obtain guidance on improving board effectiveness?
A Singapore-based B2B growth expert, Dean Cheong leads VOffice as CEO, helping organizations grow faster through structured sales execution, CRM transformation, and market expansion strategies. Backed by formal training in finance and business banking from Nanyang Technological University, he focuses on building performance-driven systems that support long-term commercial success.