
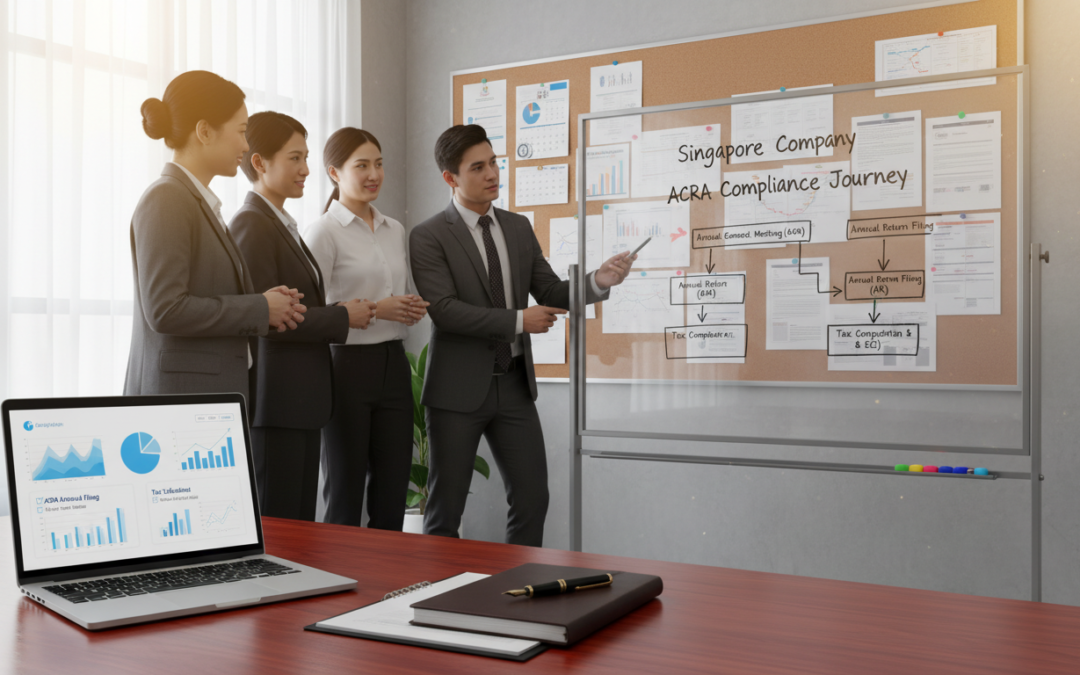
“To improve is to change; to be perfect is to change often.” — Winston Churchill
This guide turns regulatory dates into practical steps for a modern finance team. It explains what an acra compliance timeline singapore companies means day to day and why it matters beyond form-filling.
Directors, founders and finance managers need a clear annual playbook. Use this long-form, step-by-step reference as an internal checklist throughout the year.
The article covers two core obligation types: recurring annual milestones like AGMs and annual returns, and trigger-based filings after company changes.
Non-adherence risks real harm: damaged reputation with banks and investors, operational delays and legal exposure for directors. We highlight common risk areas such as late notifications, outdated registers, missed annual lodgements and inaccurate filings.
Key Takeaways
- Understand the day-to-day meaning of regulatory deadlines for your business.
- Use this guide as a year-round internal playbook to reduce risk.
- Focus on both annual milestones and trigger-driven filings.
- Non-adherence damages reputation and can cause legal exposure.
- Prioritise registers, timely notices and accurate lodgements to stay secure.
What the ACRA compliance timeline means for a Singapore company today</h2>
Regulatory deadlines shape day-to-day trust signals that affect finance, banking and vendor relationships.
Why it matters: Timely filings and accurate records support reputation, ease onboarding with suppliers, and pass banking due diligence. Missed actions attract penalties and can harm stakeholder confidence.
Core rhythm vs event-driven obligations
The core annual rhythm covers governance milestones such as AGMs and annual returns. These are predictable and should feed your calendar.
Event-driven obligations arise from changes in directors, shareholders or addresses. These trigger short windows for updates and need fast responses.
Where things go wrong and who owns it
- Typical failure points: unclear ownership, missed internal deadlines, and assuming the secretary handles everything — this is why many companies fail.
- Accountability: directors are legal owners; the company secretary stewards process; finance supplies the numbers; auditors provide assurance.
How to use this guide: Bookmark the calendar, set automated reminders, and keep signed records of approvals to cut risk and ensure on-time submission of filings.
acra compliance timeline singapore companies: a practical calendar of recurring and trigger-based filings</h2>
Start by building a compact annual calendar that turns filing dates into manageable tasks.
Begin with an incorporation baseline: record owners, nominate owners for each task, choose tools (shared diary, task tracker) and create a basic checklist. A shared calendar with owners and reminders keeps work visible and reduces error.
Setting the baseline
What to set up right away: assign an owner for filings, create a checklist of actions, and link templates for minutes and resolutions.
Trigger events that reset deadlines
- Director appointments or resignations
- Registered office address changes
- Share allotments or transfers
- Company name or key officer changes
Annual milestones and buffers
Diary annual milestones such as accounts finalisation, AGM, and annual returns backwards from their due dates. Build internal buffers so approvals and signing occur before legal deadlines.
A starter pack of necessary documents
Keep resolutions, updated registers, supporting proofs and approval evidence ready. This solves common gaps where many companies fail by relying on memory or last‑minute action.
Practical reminders: set 14‑day change notices, quarterly reviews and a year‑end audit/tax/ACRA alignment meeting to avoid rushed filings and penalties.
Notifying ACRA of company changes within the required timeframe</h2>
Notifying the registry of changes promptly keeps your public records reliable and your partners confident.
Common updates often missed: registered office address, officer appointments or resignations, shareholder movements and basic company particulars. These entries matter because third parties and regulators use them to verify authority and status.
Why “within 14 days” matters
The 14-day expectation exists because the public register is used for due diligence, banking checks and market trust. Delays create gaps that increase risk for the business and its counterparties.
Turning the effective date into deadlines
Use the effective date of change as the starting point. Set an internal deadline two business days earlier to allow approvals and signing. That converts an event into a clear filing date and prevents last‑minute misses.
Using BizFile+ to lodge updates
High-level process: prepare supporting documents, select the correct transaction type on BizFile+, lodge the update and save the acknowledgement for your audit trail.
Consequences when companies fail to update
When entities delay filings, the result penalties imposed can follow and inaccuracies linger on public records. Treat each change as a mini-project with an owner, checklist and a diary reminder for the 14‑day mark.
For practical policies and terms that support your internal process, review our terms and conditions.
Maintaining statutory registers and corporate records under the Companies Act</h2>
Statutory registers form the verifiable record of who owns and runs a firm. They are primary evidence for authority, ownership and corporate decisions. Keep them accurate to support every routine check and formal filing.
Registers you must keep current
- Members (shareholders): names, share classes and holdings.
- Directors and secretaries: appointments, resignations and service addresses.
- Auditors and CEOs: appointments and tenure details.
- Controllers/beneficial owners: persons with significant control and their particulars.
Updating registers via BizFile+ within 14 days
Use the event date as your clock start. The Companies Act expects updates on the public register within 14 days of a change. Mirror each BizFile+ submission in your internal registers to avoid mismatches.
Record-keeping systems that reduce errors and missed updates
Adopt a single source of truth: a controlled folder or register with versioning and a documented change log.
Use templates for minutes, resolutions and appointment letters. Require sign-off and save BizFile+ confirmations with each change.
Consequences of outdated records
Outdated records attract practical friction: slow onboarding, failed due diligence and negative publicity.
More seriously, result penalties imposed can reach up to S$5,000 per breach. Treat every change as a mini project with owner, checklist and the necessary documents stored for audit.
| Register | Key items to store | Retention/action |
|---|---|---|
| Members | Share register, share certificates, transfer deeds | Update within 14 days; keep originals and scanned copies |
| Directors & Secretaries | Appointment/resignation letters, ID, consent forms | File immediately; record service addresses; keep change log |
| Auditors & CEOs | Appointment notices, engagement letters | Retain for term and seven years after |
| Controllers / Beneficial Owners | Declaration forms, supporting IDs, ownership proofs | Confirm annually and update within 14 days of change |
Annual General Meetings and governance milestones that drive your timeline</h2>
A properly run annual meeting unlocks the approvals needed for filings and reduces later disputes.
What an AGM achieves
An AGM presents the financial statements and secures shareholder approval for the year‑end results. It confirms key decisions such as dividend declarations, director reappointments and auditor ratification.
How private firms may dispense with AGMs
Private companies with a simple shareholder structure can pass a majority resolution to dispense with a formal AGM. Record the resolution and retention steps, since governance actions must still be documented and accessible.
Necessary documents to prepare and circulate
Prepare and circulate the core pack well ahead of the meeting date. Include:
- Financial statements and directors’ report
- Notice of meeting, proxy forms and proposed resolutions
- Supporting schedules, auditor’s report and any explanatory notes
Director risks and downstream consequences
Directors who neglect governance milestones risk prosecution or disqualification. Missed approvals often cascade into late annual returns and potential late‑lodgement fees.
Why companies fail at this stage
Failures typically stem from unclear ownership of the calendar, late preparation of accounts, and underestimating the time needed to circulate papers.
| Focus | Action | Timing |
|---|---|---|
| Agenda items | Present accounts; pass resolutions; reappoint auditors | On AGM date; set internal sign-off 2 weeks earlier |
| Documentation | Distribute financial statements and necessary documents | Send at least 14 days before meeting |
| Risk control | Assign owner; save signed resolutions and acknowledgements | Create a retention record immediately after meeting |
Filing annual returns with ACRA on time</h2>
Filing your annual return is a legal checkpoint that keeps public records accurate and your organisation in good standing.
Who must file: All incorporated entities — a singapore company, variable capital funds (VCCs) and limited liability partnerships (LLPs) — must submit annual returns or declarations. This is a core statutory duty, not an optional task.
What the return depends on
Successful lodgement relies on current corporate particulars, completed governance steps (AGM or resolutions) and verified financial figures. Missing any of these often causes delays or corrections.
Internal workflow model
Company secretary coordinates and prepares the draft return. Finance supplies reconciled numbers and supporting schedules.
Directors review, sign off and authorise submission. Keep submission to the statutory portal only after director verification.
| Role | Key task | Timing |
|---|---|---|
| Company secretary | Prepare draft; collate documents | Internal deadline: 10 business days before statutory due date |
| Finance | Provide reconciled figures | Complete 12 business days before due date |
| Directors | Review & verify | Sign-off 5 business days before lodgement |
Return Singapore readiness checklist
- Reconcile officers and member records with internal registers.
- Confirm registered address and principal particulars.
- Validate statements and financial totals against ledgers.
- Secure director approvals and save digital sign-offs.
Evidence retention: Archive BizFile+ acknowledgements, all approvals and internal sign-off records. These form your defence if details are queried later.
Late annual lodgements and ACRA’s two-tier penalty framework</h2>
A single missed deadline can cascade into multiple failures across governance and reporting.
| When lodged | Penalty (effective 30 April 2021) |
|---|---|
| Within 3 months after due date | $300 |
| More than 3 months after due date | $600 |
Why this matters
The framework targets timely action and aims to encourage on-time filing of annual returns.
Late submissions create compound risk: missed AGMs, delayed approvals and out-of-date registers often follow one slip.
Practical prevention steps
- Identify the earliest dependency (finalised accounts or sign-offs).
- Set internal cut-offs well ahead of the statutory due date.
- Assign a single owner to chase approvals and complete filing annual returns on time.
Remember: the aim is not just to avoid result penalties imposed, but to preserve governance credibility and a reliable reporting rhythm.
Preventing false or misleading statements in ACRA filings</h2>
A single inaccurate entry can undo months of careful record-keeping and trust-building.
What counts as false or misleading information?
Examples include incorrect officer details, outdated shareholdings, declarations that do not match supporting records, or financial figures that fail to reconcile to ledgers.
Why errors happen
Rushed submissions, reliance on stale spreadsheets and inadequate review cause most mistakes. In practice, many companies fail because they skip simple verification steps.
Consequences for those who submit or authorise false entries
Penalties are severe: fines up to S$50,000 and possible imprisonment up to 2 years for submitting or approving false or misleading documents.
Practical controls to reduce risk
- Dual-review key fields: preparer (secretary/finance) and an independent reviewer (director or second checker).
- Reconcile registers and financial figures before filing.
- Require documented sign-off with date and identity for every submission.
- Segregate duties to avoid a single point of failure.
- Adopt a “stop-the-line” rule: pause filing if data is uncertain and correct registers first.
| Risk | Control | Owner |
|---|---|---|
| Incorrect officer details | Confirm IDs and consent letters; update internal register before filing | Company secretary |
| Outdated shareholdings | Reconcile share register to transfer deeds and statements | Finance & secretary |
| Unreconciled figures | Monthly reconciliations and pre-file verification checklist | Finance |
Linking ACRA deadlines with corporate income tax and tax return Singapore obligations</h2>
Linking corporate filing dates with tax deadlines prevents last‑minute rushes and inconsistent numbers.
How compliance milestones intersect with the corporate income tax cycle: governance approvals, final accounts and public filings form the inputs for corporate income tax work. Treat each approval as a trigger for tax computation so teams do not run two separate calendars that clash.
Using a “guide tax return” approach
Build a single sequence: finalise accounts → secure director/shareholder approval → lodge registry filings → prepare tax calculations. This guide tax return method reduces rework and keeps figures consistent across records.
What to prepare to let tax filing play its part
- Reconcile revenue and expense ledgers early.
- Confirm fixed asset schedules and depreciation entries.
- Document material judgements and one‑time adjustments.
For cross‑border groups, treat Malaysia items as comparative context only and maintain separate jurisdiction calendars for income tax Malaysia and related corporate income matters.
Outcome for a responsible business owner: a unified calendar lowers error rates, eases sign‑offs and helps tax return Singapore work smoothly without compromising registry accuracy.
Audit readiness as part of compliance Singapore company best practice</h2>
Good audit readiness turns an annual scramble into a predictable, low-risk process for boards and finance teams. It strengthens accuracy, improves document quality and reduces last-minute corrections before statutory filings.
Understanding core types and their roles
Know the key types audits and why each exists. Statutory audits verify financial statements. Internal audits test controls and process effectiveness. GST audits focus on tax accuracy. Forensic audits investigate suspected fraud.
How audits build trust and support filings
Audits build trust and help ensure records match lodged figures. Well-prepared working papers reduce queries and shorten lodged review cycles.
Coordination points and an operating rhythm
Key coordination steps:
- Pre-audit planning: agree scope and schedules with auditors.
- Interim checks: supply reconciliations and trial balances.
- Final fieldwork: provide signed approvals and final figures.
- Post-audit: secure management sign-off and archive working papers.
| Role | When | Deliverable |
|---|---|---|
| Finance | At close | Final schedules, reconciliations |
| Auditor | Pre-fieldwork | Request list, testing plan |
| Company secretary | Before lodgement | Approved figures, signed minutes |
Building a repeatable compliance system to stay on track year-round</h2>
A repeatable system turns annual obligations into a simple, dependable routine for the whole leadership team.
Creating a master compliance calendar with owners and contingencies
Blueprint: map each recurring and trigger task to an owner — director, secretary, finance or auditor — and note dependencies.
Include fallback owners for leave or travel. Add buffers for approvals so work completes ahead of statutory windows.
Necessary documents checklist for filings, meetings, and record updates
Keep a task-linked list of necessary documents: resolutions, updated registers, meeting packs and filing confirmations.
Store scanned originals and BizFile+ acknowledgements within 14 days of any register change.
When to seek professional support to prevent costly mistakes
Use a corporate secretary, auditor or tax adviser for complex restructures, share transfers or when in‑house capacity is stretched.
Professional help reduces the chance of result penalties imposed and reputational harm.
Tracking regulatory change as obligations evolve
Subscribe to registry updates, review processes annually and refresh templates and checklists whenever rules change.
For a practical annual playbook, see our your annual regulatory compliance timeline.
Conclusion</h2>
Simple routines and named owners make statutory duties routine rather than risky.
The central takeaway: split the year into an annual rhythm and short 14‑day trigger windows, then assign clear owners for each task.
Many companies fail when change notifications are missed, registers go stale and annual returns slip because internal dependencies are weak.
Next steps you can action today: create a shared calendar, assign owners for each item, gather the necessary documents and schedule a quarterly review.
Directors should treat this as governance protection: accurate filings reduce legal exposure and keep the public record dependable.
If your team is stretched, engage competent corporate secretarial and accounting support to avoid avoidable mistakes and penalties.
FAQ
What does the ACRA compliance timeline mean for my Singapore company today?
Who is responsible for meeting statutory filing and reporting deadlines?
What are the key recurring events I should diarise every year?
Which trigger events require immediate notification and why does the 14‑day window matter?
How should we maintain statutory registers and corporate records?
What happens if annual returns or other filings are lodged late?
What counts as a false or misleading statement in corporate filings?
How do corporate filing deadlines link with corporate income tax and tax returns?
When is an audit required and what types of audits should we expect?
What documents should be ready before an AGM or director meeting?
How can we prevent common failures that lead to penalties?
Are there practical tools for lodging updates and keeping records accurate?
What are typical penalties or consequences for failing to update records or submit filings?
When should a business seek professional support for its filing obligations?
How do changes to regulatory requirements affect our ongoing obligations?
A Singapore-based B2B growth expert, Dean Cheong leads VOffice as CEO, helping organizations grow faster through structured sales execution, CRM transformation, and market expansion strategies. Backed by formal training in finance and business banking from Nanyang Technological University, he focuses on building performance-driven systems that support long-term commercial success.